DREAM ON
₹5 lakh personal loan in minutes
100% digital onboarding

Personal Loan
Provided by multiple lenders.

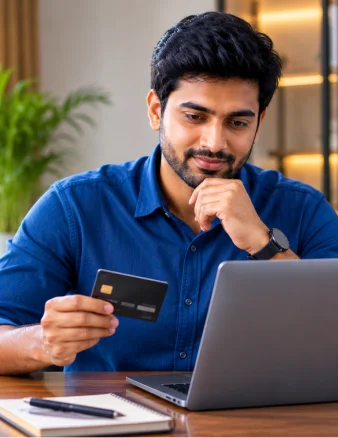
Getting a credit card with no annual fee sounds like an obvious win. Why pay for something when you can get it for free? But there is another side to the story. A card with an annual fee may come with rewards, cashback or benefits that can easily make up for the cost. So the real question is not “Does this card charge a fee?” but “Am I getting enough value to justify it?” Once you look at it that way, an annual fee becomes less of a charge to avoid and more of a cost worth calculating.
A credit card annual fee is a yearly charge levied by the card issuer for maintaining and using the card. The amount depends on the card and its features. It can range from a few hundred rupees to several thousand rupees for premium cards. Some cards waive this fee if you meet a specified spending threshold, while some are offered as lifetime-free cards.
An annual fee may sound like something you should immediately eliminate. But this is not always true. The better question is: What am I getting for the fee? An annual fee can make sense when:
If you regularly earn enough cashback, reward points or other benefits to cover the annual charge, the fee may be worthwhile.
Some cards waive the next year’s fee once you cross a specified annual spending limit. This can make a paid card effectively free for disciplined, regular users.
Some cards waive the first-year fee or offer an initial benefit that can make the cost worthwhile, particularly if you already planned to use the card.
A premium card is useful only when its benefits fit your lifestyle. Paying for travel perks you never use is hardly a financial win.
JioFinance can help you explore and compare credit card options, making it easier to look for a credit card that fits your needs rather than simply choosing the one with the lowest fee.
Paying the annual fee is not always inevitable. Depending on your card’s terms and your relationship with the issuer, you may have ways to reduce or eliminate it.
Many issuers offer an annual-fee waiver when your spending crosses a specified limit during the year. If you already spend around that amount, this can be an easy way to avoid the fee. Do not spend unnecessarily just to unlock a waiver.
Some cards come with a first-year annual-fee waiver. Others may waive the following year’s fee if you meet a particular spending requirement. Check the offer period and eligibility conditions before applying.
Certain issuers may allow accumulated reward points to be used as a credit against the annual fee. This is not available on every card, so check the card’s terms before counting on it.
Have you held the card for a long time and maintained a good repayment record? It may be worth contacting customer service and asking whether the fee can be waived. Issuers may offer a waiver or another solution to retain eligible customers.
If the fee no longer makes sense, ask whether another card from the same issuer would suit you better. You could move to a card with more suitable benefits or downgrade to one with fewer features and no annual fee.
A “waiver” may come with conditions. The spending requirement may exclude certain transactions. The issuer may waive the base fee but still apply GST. Check exactly what is being waived and what you still have to pay.
A credit card works best when it is a payment tool, not an excuse to spend beyond your means. Two simple rules can help you keep your usage in check:
The 2/3/4 rule suggests limiting new credit card applications to two in 30 days, three in 90 days, and four in 24 months. The idea is to space out applications rather than repeatedly applying for cards within a short period.
The 50-30-20 rule divides your income into three broad buckets:
The difference is simple: a paid credit card charges an annual fee, while a zero-fee or lifetime-free card does not charge this recurring fee, subject to its terms.
But “zero fee” does not automatically mean better. A paid card may offer stronger rewards or benefits. A zero-fee card may be more suitable if you want basic credit access without paying for features you will not use.
An annual fee is not automatically a red flag. Sometimes, it is simply the price of benefits you get. The real mistake is paying it without knowing what you are getting in return or spending extra just to avoid it.
Before choosing a card, compare its fee, benefits, waiver conditions and your own spending pattern. Use JioFinance to explore financial products in one place and make more informed choices about the credit card that suits your needs. And for everyday payments, JioFinance’s UPI lets you scan, pay, split bills and track transactions conveniently.
100% digital onboarding
Instant approval, flexible repayment.

100% digital FDs

Buy, sell, SIP in digital gold in minutes

100% digital FDs

100% digital FDs