DREAM ON
₹5 lakh personal loan in minutes
100% digital onboarding

Personal Loan
Provided by multiple lenders.

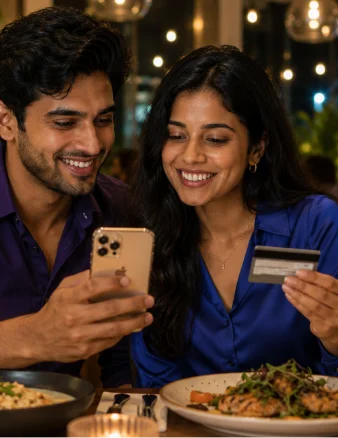
Groceries and dining together eat up a fair chunk of most household budgets. Home delivery can push the total even higher. Put that spending on the right card, and a genuine 5% to 10% of it comes back as cashback or rewards. Choose the wrong card, however, and the same spending may earn little or nothing, without you realising why.
The key is choosing a card whose rewards actually match your spending habits.
Most generic cashback cards return somewhere around 0.25% to 0.5% on everyday spending, a single reward point per ₹100, roughly. Cards built specifically around groceries and dining return considerably more, commonly landing between 5% and 10% on these categories specifically.
The gap compounds fast: on ₹10,000 a month in grocery spending, that's the difference between roughly ₹300 a year and closer to ₹6,000, just from choosing the right card for the same spending you were doing anyway.
Choosing a groceries and dining credit card is less about the headline reward rate and more about how well the card fits your everyday spending. Check these 5 factors before you apply for a credit card:
A large share of grocery spending now happens through food-delivery-linked quick-commerce apps rather than a physical supermarket. The strongest cards specifically reward this shift; some touch 10% on these platforms.
A card that only rewards one specific app leaves a gap if you also shop at a physical store or a different platform. A card rewarding groceries more broadly tends to serve mixed shoppers better.
Beyond straightforward cashback, several cards bundle in a separate dining privileges programme offering 15% to 25% off at partner restaurants. This stacks on top of whatever cashback or points the transaction itself earns.
Many high headline rates only apply above a minimum transaction value, or up to a monthly cap. A 10% rate capped at ₹1,000 a month effectively stops rewarding you the moment you cross ₹10,000 in that category for the month.
This is where a lot of cards quietly disappoint. Grocery purchases are sometimes excluded from a card's general "online spends" bonus category via Merchant Category Codes, even when the card is marketed as a broad cashback option. It is worth checking the fine print rather than assuming groceries are automatically covered.
Did you know? You can earn up to 2,000 JioPoints when you get your credit card activated, where 4 JioPoints carry a value of ₹1.
Reward structures can vary significantly across card types. So, comparing the rate, eligible categories, caps and redemption terms is essential before choosing a card.
| Card Type | Typical Rate on Groceries/Dining | Common Caveats |
| Food-delivery co-branded cards | Up to 10% on the partner app (food delivery, quick-commerce grocery) | Usually requires a minimum transaction value; monthly cap common |
| Dedicated grocery/dining cashback cards | 5%–10% across a wider set of merchants | Category exclusions and monthly caps still apply |
| Premium/lifestyle cards | 5x–10x reward points on dining specifically | Points need redemption to realise value; less useful for groceries |
| General cashback cards | 1%–1.5% on groceries and dining, alongside a higher rate elsewhere | Often not optimised specifically for this category |
The right card depends on where you actually spend, how rewards are credited and whether the benefits outweigh the fees. Consider these factors to choose the right credit card for your spending habits:
If quick-commerce and food delivery dominate your grocery spending, a card rewarding that specific ecosystem heavily makes more sense than a generalist option. If you split between a supermarket and a couple of apps, a broader grocery cashback card usually serves better.
Check whether cashback lands as a statement credit or a wallet balance. Statement credit is more flexible and directly reduces what you owe. Some cards historically credited cashback to an in-app wallet instead, which is less useful.
Don't chase the headline rate blindly. A 10% rate capped at ₹500 a month is worth less over a year than a steady 5% with no cap, once your spending crosses that low threshold.
Factor in the annual fee against realistic usage. Many of the stronger grocery and dining cards carry a modest annual fee that's waived above a spending threshold.
Check whether that threshold is realistic for your actual annual spend before assuming the card is effectively free.
Reward structures, caps, and exclusions vary so much between cards even within the same category. Comparing the fine print matters more than comparing headline percentages. JioFinance's card comparison feature lists grocery and dining-focused credit cards side by side along with fees, reward caps, and pre-qualified offers. This makes it easier to check eligibility before applying rather than assuming a well-advertised card will actually approve you.
Once a card is linked, you can also easily keep track of spending and status through the JioFinance application. That's a practical way to confirm after a couple of months whether groceries and dining are actually earning at the rate you expected, or whether a monthly cap is quietly capping your returns earlier than you'd assumed.
Groceries and dining are recurring, unavoidable expenses, which is exactly what makes the right card worth the effort of comparing. A card that genuinely rewards how you actually shop, rather than the one with the flashiest headline percentage, is what turns routine monthly spending into a meaningful annual saving. That's better than a marginal card that quietly caps out by mid-month.
100% digital onboarding
Instant approval, flexible repayment.

100% digital FDs

Buy, sell, SIP in digital gold in minutes

100% digital FDs

100% digital FDs