DREAM ON
₹5 lakh personal loan in minutes
100% digital onboarding

Personal Loan
Provided by multiple lenders.

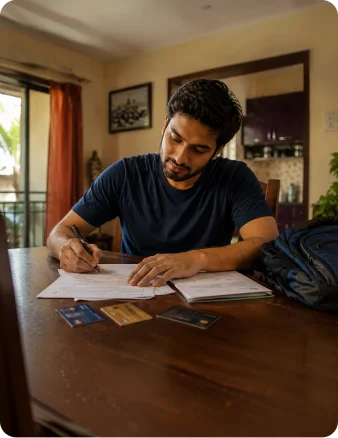
When Manish received his annual bonus, he saw an opportunity to clear his personal loan ahead of schedule. He had already been repaying it for two years and had only six EMIs left. While the thought of becoming debt-free sooner was appealing, his wife suggested checking the prepayment charges and comparing them with the interest he would save. It turned out to be a useful pause.
Prepaying a loan may sound like a smart financial move, but the numbers do not always make it worthwhile. Before you rush to clear the dues, check the rules, charges, and, most importantly, whether prepayment actually works in your favour.
Loan prepayment means paying part or all of your outstanding loan before the scheduled repayment date. A part payment reduces the principal while the loan continues, whereas foreclosure means paying the entire outstanding amount and closing the loan early. The applicable terms depend on the lender, loan type, and regulatory rules.
| Option | What It Means | Loan Status |
| Prepayment | Paying before the scheduled tenure | May be partial or full |
| Part payment | Paying a portion of the outstanding principal | Loan continues |
| Foreclosure | Paying the entire outstanding amount | Loan closes |
From January 1, 2026, RBI's new prepayment rules have made it easier for certain borrowers to repay their loans early without paying a prepayment charge. The key change applies to floating-rate loans taken by individuals for non-business purposes. If your personal loan falls under this category, the lender cannot charge you for making a full or partial prepayment.
For loans that are not covered by the RBI's no-charge provisions, prepayment charges still apply according to the lender's approved policy. RBI's directions require such charges, where applicable, to be transparently disclosed in the relevant loan documentation.
So, before making a payment, check:
A fixed-rate personal loan generally keeps the interest rate unchanged for the agreed period, while a floating-rate loan can change with the applicable benchmark or lending conditions. This distinction matters because RBI's 2026 prepayment-charge directions specifically protect qualifying floating-rate loans. For fixed-rate loans, prepayment charges may still apply according to the lender's applicable terms.1
There is no universal “yes” here. The right answer depends on your financial situation.
| Prepayment May Make Sense If | You May Want to Hold Off If |
| You have enough surplus money after maintaining an emergency fund. | Prepayment would wipe out most of your emergency savings. |
| A substantial portion of the loan tenure is still left, giving you more potential interest to save. | The loan is already close to maturity, leaving limited interest to save. |
| The applicable prepayment charges are low or zero. | Applicable charges significantly reduce the benefit. |
| You want to eliminate an EMI and free up monthly cash flow. | You need the money for an upcoming major expense. |
| You do not have more expensive debt that deserves priority. | You would have to sell an investment or take another loan to arrange the prepayment amount. |
1. Myth: Prepayment is always financially beneficial.
Reality: Not necessarily. The actual benefit comes only after you have evaluated charges, remaining interest and your available savings.
2. Myth: You must close the entire loan to reduce the interest burden.
Reality: You can also go for part payment to reduce the outstanding principal and, consequently, the interest payable over the remaining tenure.
3. Myth: Every personal loan has the same prepayment charges.
Reality: Charges depend on the loan terms, lender, interest-rate type and applicable RBI provisions.
4. Myth: Prepaying automatically improves your credit score.
Reality: Closing a loan is not a guaranteed shortcut to a higher credit score. Your broader repayment history and credit behaviour continue to matter.
Before putting your extra money towards the loan, run through this quick checklist:
Prepaying your loan is only one part of managing your finances. Click here to learn how JioFinance offers tools and financial products that can help you manage your money better.
Prepaying a personal loan can be a smart way to reduce future interest and free yourself from an EMI sooner. But being debt-free is not the only goal; staying financially comfortable matters too. Check the applicable 2026 rules, calculate your actual savings and keep enough cash for emergencies before making a decision. Whether you are planning a new loan, managing credit or looking for ways to make your money work better, JioFinance brings multiple financial services together on one platform.
100% digital onboarding

Instant approval, flexible repayment.


100% digital FDs


Buy, sell, SIP in digital gold in minutes


100% digital FDs


100% digital FDs